His pay looked permanent. The vesting schedule disagreed.
The Situation
Adeola, Ade to everyone at work, is 33, a senior software engineer in Santa Clara, and he joined NVIDIA in late 2024 on the newer front-loaded grant structure. His wife works in biotech; their first child is due in the spring. On paper, the last two years have been the best of his life. Between base salary, his Year 1 and Year 2 equity tranches vesting into a stock that kept climbing, and a refresher grant, household income cleared $610,000 in 2026.
They were doing a lot right. Both 401(k)s maxed, no consumer debt, a healthy emergency fund, and an offer accepted on a $2.1 million house in Sunnyvale with a jumbo mortgage pre-approval sized against that $610,000.
The Gap We Found
Ade's grant vests 40/30/20/10 across four years. Nobody had drawn that curve out for him. The two years he was budgeting from were the two biggest years the grant will ever produce, and in 2028 the 20% and 10% tranches land together against a refresher floor of roughly $80,000 a year. Even holding the stock price flat, his equity income falls by more than half. His lender underwrote the peak. His mortgage would still be there at the trough.
What We Did
We built the actual vest calendar, year by year, for every grant he holds: not the offer-letter summary but the tranche-level schedule, with the guaranteed refresher as the floor rather than the expectation. Then we ran three stock scenarios against it: flat, down 40% (NVIDIA did exactly that in 2022), and up. In the flat case his 2028 equity income was $91,000. That number did the convincing.
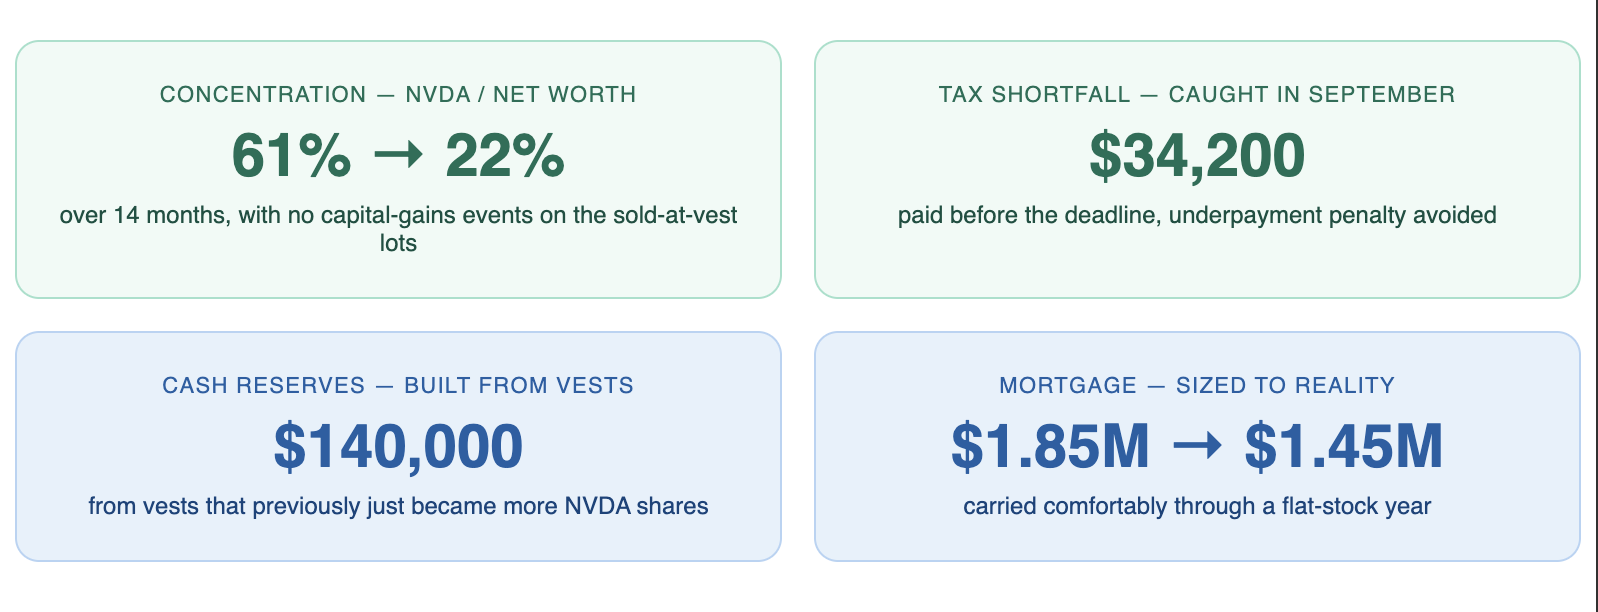
We re-sized the house. Not "buy less house" as a lecture. We sized the mortgage against base salary plus the guaranteed refresher floor, which supported $1.45 million comfortably instead of $1.85 million. The difference funded a larger down payment out of shares he was going to have to sell anyway.
Then we made the vests work instead of pile up. Ade now sells at vest as a standing rule, which means zero capital gains on those lots because the shares are sold at the price they were already taxed on. Proceeds route into a direct indexed portfolio that harvests losses automatically, a treasury ladder for the down payment and the baby's first two years, and the ESPP, which, with its lookback and 15% discount, is the best-priced thing he can buy. Alphanso's AI agents parse his payroll after each vest and flag the withholding gap before the quarterly deadline rather than in April.
The Result
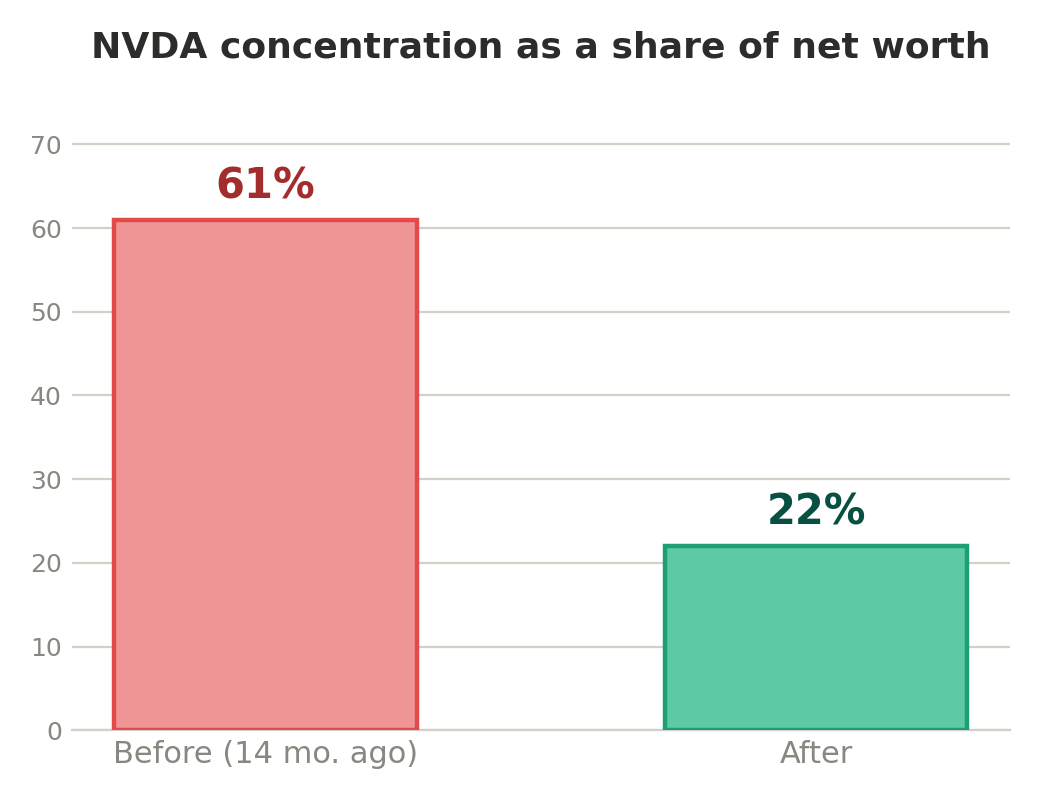
- Concentration in NVDA dropped from 61% of net worth to 22% over 14 months, without a single capital gains event on the sold-at-vest lots
- A $34,200 federal estimated tax shortfall caught in September and paid before the deadline, avoiding the underpayment penalty
- $140,000 in cash reserves built from vests that previously just became more NVDA shares
- A mortgage he can carry in a year when the stock does nothing, and a plan that does not require it to
Why This Worked
Ade's mortgage broker saw income. His payroll system saw withholding. His brokerage saw shares. None of them saw a four-year curve bending downward under a 30-year loan. That is not a failure by any of them. It is the space between them, and it is the only place that question can be answered. Because Alphanso is flat-fee and fiduciary, the advice to buy less house cost us nothing and gained us nothing. It was just the right answer.
If your vesting schedule and your spending plan have never been put on the same page, let's talk.
This case study is a composite illustration based on real Alphanso client scenarios. Names and identifying details have been changed for privacy. Results are not guaranteed and will vary based on individual circumstances. All investing involves risk, including the possible loss of principal. Alphanso Inc is a registered investment adviser.
Schedule demo with our advisors
What to expect